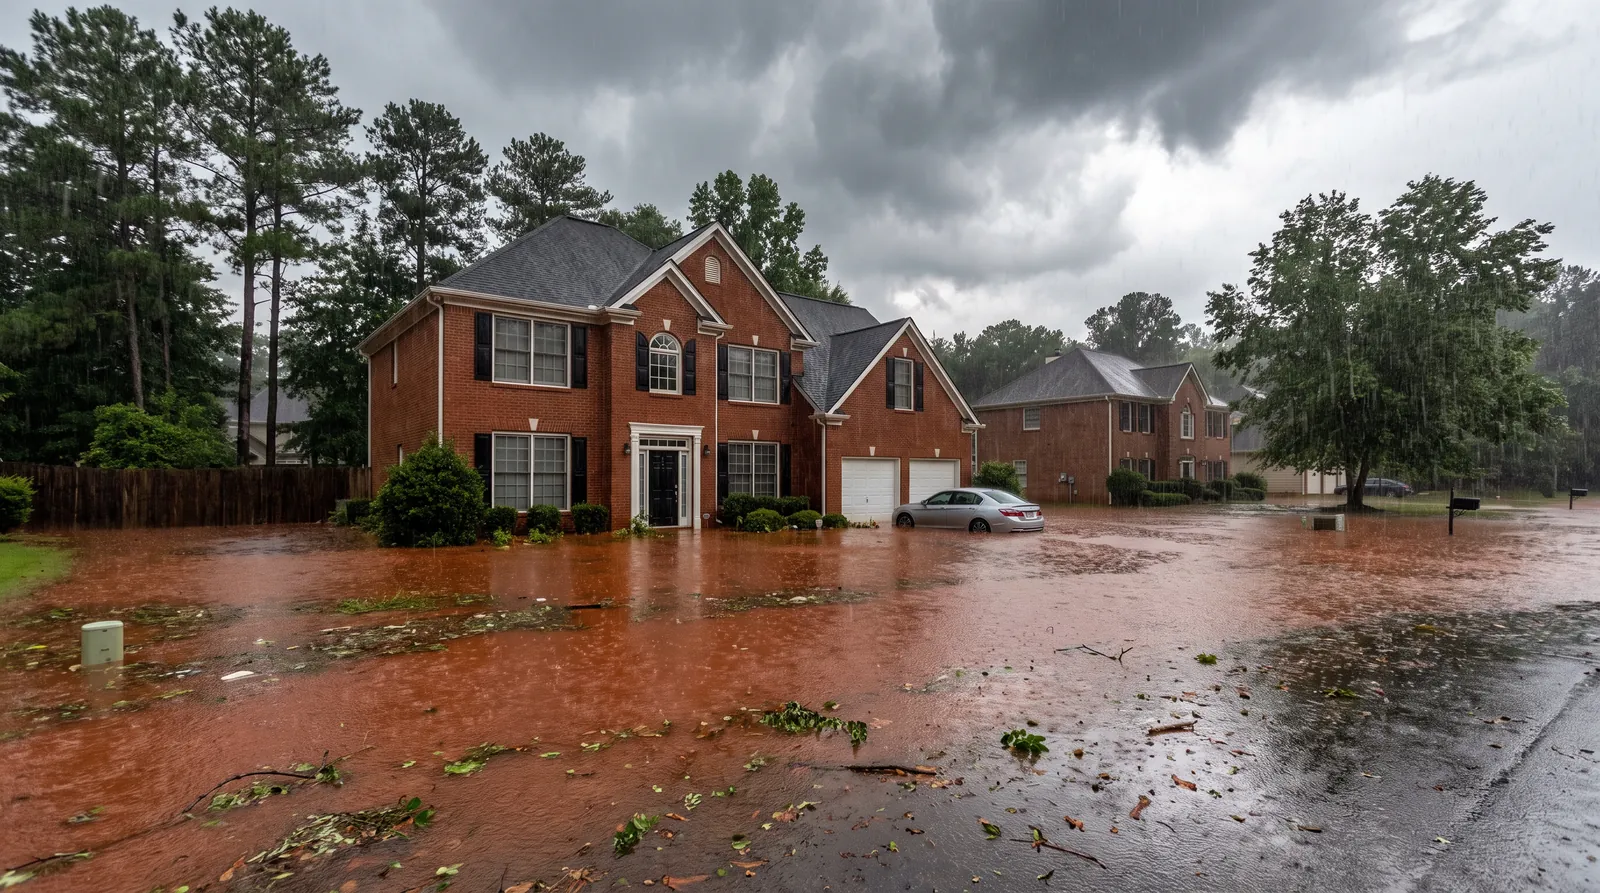
Floodwater rising near a Georgia home
Home / Flood Insurance

Georgia Flood Insurance: The coverage your home policy leaves out.

Your homeowners or renters policy won't pay a flood claim. Georgia's insurance regulator says so plainly. We'll help you price NFIP and private flood for your address, from creekside lots to hilltop subdivisions.

$250K
NFIP Building Max
30 Days
NFIP Waiting Period
$100K
NFIP Contents Max
Free
Coverage Review With A Local Agent
The Quick Answer

Homeowners and renters insurance do not cover flood. The Georgia Office of Commissioner of Insurance and Safety Fire says exactly that. Rising water from creeks, rivers, or heavy rain needs a separate policy through the National Flood Insurance Program (NFIP) or a private flood insurer. NFIP limits are $250,000 for the building and $100,000 for contents, and most policies take effect 30 days after purchase (a policy bought as part of a mortgage transaction has no wait). A large share of flood claims come from outside high-risk zones, and FEMA estimates one inch of water can cause about $25,000 of damage. In Clayton County the risk is mostly flash flooding from heavy rain, local creeks, and the Flint River headwaters, and you can look up any address on the FEMA Flood Map Service Center. Sewer or drain backup is not flood; it needs its own endorsement. All Access Agency, a local insurance agency in Morrow, quotes flood coverage free at (770) 576-3416.

Home policy pays
$0 for flood
NFIP limits
$250k building / $100k contents
Waiting period
Typically 30 days
Free quotes
(770) 576-3416
Georgia Flood Insurance, The Short Version

The coverage most south metro homes don't have. Yet.

Here is the sentence that surprises almost everyone, so we will put it first: your homeowners policy pays nothing for flood damage. Not a reduced amount. Nothing. Rising water from a creek, a river, or a storm that overwhelms the drainage is excluded from standard home and renters policies. Georgia's insurance regulator says it plainly: homeowners policies do not cover flood. Flood coverage is its own policy, through the federal NFIP or a private flood insurer.

The second surprise is who floods. Lenders only require flood insurance in high-risk zones, but a large share of flood claims come from outside those zones. You don't need to live on a creek bank. A stalled summer thunderstorm, a tropical storm crossing inland, or a low spot on the block can put water where it has never been. And FEMA estimates that one inch of water can cause about $25,000 in damage.

Georgia sees this kind of flooding more than people expect. When Hurricane Helene came through in September 2024, Atlanta got 11.2 inches of rain. Closer to home, the Flint River begins in urban streams piped beneath Hartsfield-Jackson Airport, just minutes from Morrow, and Clayton County is laced with creeks, including Jester Creek in and near Morrow. The water is closer than most people think.

That is the whole offer here. All Access Agency is a local insurance agency. We'll look up your flood zone, help you weigh NFIP and private flood options, size the building and contents limits to your actual house, and show you how the flood policy fits next to your home policy. We'll also check the gap people confuse with flood: sewer and drain backup. A flooded car, by the way, is an auto policy matter. Call (770) 576-3416 and we'll walk through it. It takes about 15 minutes to get started.
What a flood policy covers. And the three things it never does.

A flood policy is simpler than a homeowners policy — two main coverages plus a code-upgrade helper — but its limits, definitions, and gaps are exactly where claims go sideways. Here is the map.

Building
Up to $250k NFIP

Building Property

The structure itself: foundation, walls, electrical and plumbing systems, furnace and water heater, built-in appliances, and attached fixtures. The NFIP caps this at $250,000; if your home would cost more to rebuild, private flood can go higher. The yard, decks, fences, and landscaping are not covered.

Contents
Up to $100k NFIP

Personal Property

Furniture, clothing, electronics, and the rest of what you own, on its own limit and deductible. The catch: the NFIP pays contents at actual cash value — depreciated worth, not replacement price. Private flood policies often pay replacement cost, which is one of their strongest selling points.

ICC
Up to $30k

Increased Cost of Compliance

If a flood leaves your home substantially damaged, the city can require you to rebuild to current floodplain code: elevated, floodproofed, or relocated. ICC adds up to $30,000 toward exactly those costs, and along creek floodplains it is the coverage nobody knows they have.

Definition
Read this one

What Counts as a Flood

The NFIP definition: surface water covering two or more acres of normally dry land, or two or more properties, at least one of them yours. Rising water from a creek, a river, a lake, or overwhelmed drainage qualifies. A pipe bursting inside the house does not. That claim belongs to your home policy.

Deductibles
Two of them

Building & Contents Deductibles

A flood policy carries separate deductibles for building and contents, chosen when you buy. Raising them lowers the premium; just pick numbers your savings can actually absorb the week after a flood, when the cleanup crew is also due.

Excess
Above the caps

Excess Flood

For homes that would cost more than $250,000 to rebuild, which describes many homes in Morrow and across south metro Atlanta, private flood can stack additional coverage above the NFIP limits, so a serious flood does not stop paying at the cap while the damage keeps going.

Not covered
Living costs

Temporary Housing (NFIP)

The NFIP pays nothing toward rent or hotels while your home is unlivable, a gap that surprises families at the worst time. Some private flood policies add temporary living expense coverage, a real point in their favor and one we look at for every client.

Not covered
Vehicles

Cars & Trucks

A flooded vehicle is not a flood-policy claim. It is covered by the comprehensive coverage on your auto policy, if you carry it. Comprehensive typically also pays for hail damage and falling trees, so dropping it to save a few dollars is a bet against the weather.

Not covered
Backup

Sewer & Drain Backup

Water backing up through a floor drain or sewer line is not flood, and a standard home or renters policy doesn't cover it either. It needs its own endorsement on your home policy. In a finished basement during a summer downpour, that endorsement earns its keep.

Do you actually know your flood zone?

Most homeowners are guessing. We will look up your zone, and talk through your real risk. It takes about 15 minutes to get started.
Coverage Basics

The four decisions that actually shape your flood policy.

Flood insurance looks like a commodity until you read two policies side by side. These are the choices that decide what a claim actually pays.

1. NFIP or private, and how we help you choose

The NFIP is the federal program: standardized coverage, capped limits, and federal backing. Private flood insurers compete on what the NFIP lacks: higher limits, replacement cost on contents, temporary living expenses, and in some cases shorter waiting periods.

Neither is “better.” They are better for different houses. Private insurers rate the same property with different models, so the gap between quotes can run in either direction. We start with our primary carrier, and through brokerage relationships we can also access 30+ other carriers when it isn't the right fit. We'll show you what each option actually covers before you decide.

2. The building limit, and the cap above it

Your building limit should track what it costs to rebuild the house, the same rebuild-cost logic as your homeowners dwelling limit. The NFIP stops at $250,000, and many south metro homes rebuild for more than that. If yours does, a private policy with a higher limit, or an excess layer above the NFIP, keeps the coverage running as far as the damage does.

3. Contents, the coverage everyone skips

Building and contents are separate elections, and skipping contents to save money is the most common flood-policy regret. Watch the settlement basis: the NFIP pays contents at depreciated actual cash value, while many private policies pay replacement cost. On a basement full of furniture, appliances, and electronics after a foot of water, that difference is not academic.

Renters are not exempt from any of this. A landlord's flood policy covers the building, never your belongings. A contents-only flood policy exists for exactly this.

4. Sewer and drain backup, the claim people mistake for flood

Plenty of basement water doesn't come from a creek. It comes up through a floor drain. When heavy rain overwhelms the sewer system, water can back up into your home. That is not flood under a flood policy, and it is not covered by a standard homeowners or renters policy either. It's an endorsement you add, with its own limit.

If you have a finished basement, this is often the coverage that matters most. We'll check whether you have it, what the limit is, and whether it fits what's down there.

Already have a flood policy? Send it over.

Building limit, contents basis, deductibles, and whether your sewer backup endorsement is really there. We will flag what is exposed and what is fine. No pressure either way.

Georgia Flood Risk, Honestly

Zones, creeks, flash floods, and what the map does not tell you.

You have seen the maps and heard the warnings. Here is what they actually mean for a home in Morrow or anywhere in Clayton and Henry counties.

How the zones work

FEMA maps sort property into zones. A and AE zones face at least a 1 percent annual flood chance, the “100-year” floodplain, which over a 30-year mortgage works out to roughly a 1-in-4 chance of flooding. If your home sits in a high-risk zone and carries a federally backed mortgage, your lender must require flood insurance. Shaded X is moderate risk, unshaded X is lower risk, and neither carries a mandate. You can look up any address yourself on the FEMA Flood Map Service Center.

Around here the zones follow the water you already know. The Flint River begins in streams piped beneath Hartsfield-Jackson Airport, and USGS monitors Jester Creek in and near Morrow along with Flint River sites near Jonesboro, Riverdale and Forest Park. FEMA flood studies for Clayton County have named Beaver Dam, Hurricane, Jester, Mud, Panther, Sullivan and Upton Creeks. Two streets in the same neighborhood can land in different zones, which is why we look up the actual map for your address instead of guessing from the subdivision.

Flash floods and tropical rain

Most flooding in the south metro is fast, not slow. A stalled thunderstorm dumps more rain than the ground and storm drains can take, and creeks rise within hours. Tropical systems do the same thing on a bigger scale: when Hurricane Helene came through in September 2024, Atlanta got 11.2 inches of rain. Hurricane season runs June 1 to November 30, and inland flooding is one of the main ways those storms reach us.

The mandate map and the risk map are different maps. A large share of flood claims come from outside high-risk zones, from homes where no lender ever required coverage. And because FEMA estimates one inch of water can cause about $25,000 in damage, a “minor” flood is rarely minor on the invoice.

Pricing, waiting periods, and timing

FEMA now prices NFIP policies property by property, based on elevation, distance to water, foundation type, and rebuild cost, rather than by flood zone alone. Zones still control the lender requirement, but not your price.

The bigger timing issue is the 30-day waiting period. If you wait until a tropical storm is in the forecast, the rain may arrive before your coverage does. The smart moment to buy is well before summer storm and hurricane season, not the week a storm is named.

Near a creek, a lake, or a low spot on the block?

The 30-day clock favors early buyers. Let us look up your zone and quote your options, no charge and no pitch.

Seven honest ways to lower your flood premium. Without hollowing out the policy.

In flood insurance the two biggest levers are timing and looking at more than one option, because every property is priced on its own. The rest stack on top.

1

Buy before storm season

NFIP coverage typically takes 30 days to start. A policy bought when a tropical storm is already in the forecast may not be in force when the rain arrives. Buy well before summer and hurricane season and let the calendar do half the work.

2

Compare NFIP and private flood

The two markets rate the same house with different models, and the gap can run in either direction, with different contents settlement, limits, and living-expense coverage attached. We'll lay the options side by side. Taking whatever renewal shows up unexamined is how flood premiums quietly grow.

3

Ask about assuming the seller's policy

Buying a home that already carries NFIP coverage? The policy can be assumed at closing, which is often cheaper than starting fresh at today's price. Ask before you close; it cannot be reconstructed after.

4

Get an elevation certificate if the lot favors you

Optional for NFIP pricing, but it can help: on a walkout lot that sits well above the water, or a home above the base flood elevation, the survey can lower your premium.

5

Raise the deductibles your savings can cover

Building and contents deductibles are separate elections, and raising them trims the premium. Pick numbers you could actually write checks for the week after a flood, when the cleanup crew, the furnace, and the car may all be due at once.

6

Claim the mitigation credits

Proper flood vents in enclosures, furnaces and utilities moved up out of the lowest floor, and filled-in below-grade spaces can all move the NFIP price. If you are already renovating the basement, an hour of planning can buy a lasting discount.

7

Never let it lapse

Continuous coverage protects your rating history; a lapse can cost you, and re-entry means waiting 30 days you may not have in storm season. Autopay the flood policy and forget it. This is the one policy where loyalty to the coverage itself pays.

Every flood situation is a different problem. We quote them all.

A creek nearby, a closing date, a rental, a finished basement. Each changes how the flood policy should be built.

Under contract, or watching the storm forecast?

Tell us the address and we will look up the zone, quote your options, and tell you what would make it cheaper. Straight answer, no obligation.

Flood insurance in Morrow. And across south metro Atlanta.

Flood risk is property by property here, and two streets in the same neighborhood can sit in different zones. We serve Clayton and Henry counties and all of Georgia, and we look at your actual address.

Georgia flood insurance questions. Straight answers.

Doesn't my homeowners insurance cover flooding?

No. Standard homeowners and renters policies exclude flood: rising surface water and overflow from creeks, rivers, lakes, and drainage. The Georgia Office of Commissioner of Insurance and Safety Fire states that homeowners policies do not cover flood.

The dividing line is where the water came from. A pipe bursting inside the house is sudden internal water damage and belongs to your home policy. Water coming in from outside and rising belongs to a flood policy, and only a flood policy.

Am I required to buy flood insurance?

Only if your home sits in a FEMA high-risk zone and carries a federally backed mortgage. Then the lender must require it, and will.

Outside those zones it is optional, which is the trap: a large share of flood claims come from outside high-risk zones. The mandate map and the risk map are two different maps. We'll quote it either way and let you decide with the number in front of you.

How much does flood insurance cost in Georgia?

It depends on the property. FEMA prices each NFIP policy on the home's elevation, distance to water, foundation type, and rebuild cost. Lower-risk homes generally pay less; high-risk and previously flooded addresses pay more.

Private flood insurers rate the same house with different models, so a second quote is not a formality. The gap between NFIP and private can run in either direction. We'll help you compare them.

What does an NFIP flood policy cover?

For a single-family home, up to $250,000 for the building (structure, systems, built-in appliances) and up to $100,000 for contents, each with its own deductible. It also includes up to $30,000 of Increased Cost of Compliance toward rebuilding to current floodplain code after substantial damage.

Know the two catches: contents pay at depreciated actual cash value, and the NFIP pays nothing toward temporary housing while your home is unlivable. Private flood policies often improve on both.

NFIP or private flood insurance — which is better?

Better for your house is the only version of that question that matters. The NFIP is standardized and federally backed. Private flood can offer higher limits, replacement cost on contents, temporary living expense coverage, and sometimes a lower price, but private insurers choose their risks and can decline or non-renew.

We'll walk through both for your address. The answer can change at renewal, so ask us for a free policy review instead of letting the policy ride.

Is there a waiting period for flood insurance?

Most NFIP policies take effect 30 days after purchase. A policy bought as part of a mortgage transaction has no waiting period. Private flood policies may use shorter waits.

In Georgia, the waiting period matters most in summer and hurricane season. If you buy when a tropical storm is already in the forecast, the rain may arrive before your coverage does. The time to buy is well before the storm is named.

I'm not in a flood zone. Do I still need flood insurance?

Everyone is in a flood zone; the question is which one. Zone X means lower risk, not no risk, and a large share of flood claims come from outside high-risk zones. FEMA estimates that one inch of water can cause about $25,000 of damage.

Here is the useful irony: lower-risk zones generally get lower pricing. The addresses where people skip flood coverage are often the ones where it costs the least to carry. Get the quote before deciding it isn't worth it.

Is sewer backup the same as flood?

No, and it's an easy one to mix up. Water that backs up through a floor drain or sewer line is not flood. A flood policy won't pay for it, and a standard homeowners or renters policy won't either.

Sewer and drain backup coverage is a separate endorsement you add to your home or renters policy, with its own limit. If you have a finished basement, ask about it before storm season.

Will FEMA disaster assistance cover me if I skip flood insurance?

Not meaningfully. Federal assistance requires a presidential disaster declaration, much of it arrives as loans that must be repaid, and grants are typically a small fraction of real repair costs.

Most floods, including the flash floods that hit one neighborhood after a stalled thunderstorm, never trigger a declaration at all. Assistance is a safety net, not a substitute for coverage.

Does flood insurance cover my car or temporary housing?

No on both, under the NFIP. A flooded vehicle is a comprehensive claim on your auto policy. Comprehensive typically also covers hail damage and falling trees, so think twice before dropping it.

The NFIP pays nothing toward rent or hotels while your home is unlivable. Some private flood policies add temporary living expense coverage, which is a real point in their favor.

Can a flood policy transfer when a home is sold?

Yes. An NFIP policy can be assumed by the buyer at closing. On a home that has carried flood coverage for years, assuming the existing policy can beat starting a new one at today's price.

It has to be arranged before closing, not reconstructed after. If you're buying anywhere near a creek, a lake, or a low spot, put “can I assume the flood policy?” on the checklist next to the inspection.

How do I find my flood zone?

Search your address on the FEMA Flood Map Service Center at msc.fema.gov. It shows the current flood map for your property, including whether it sits in a high-risk A or AE zone or a moderate or lower-risk X zone.

Maps are a starting point, not the full story, since a large share of flood claims come from outside high-risk zones. Flood insurance is also only available where the community participates in the NFIP. Call us and we'll look it up with you and talk through whether a flood policy makes sense for your address.

Still have questions? Call (770) 576-3416. We will give you a straight answer.

Find out what your flood risk really costs to cover.
Free, fast, and in plain English.

Tell us the address. We will look up the zone, walk through NFIP and private options, and work toward real numbers. It takes about 15 minutes to get started.