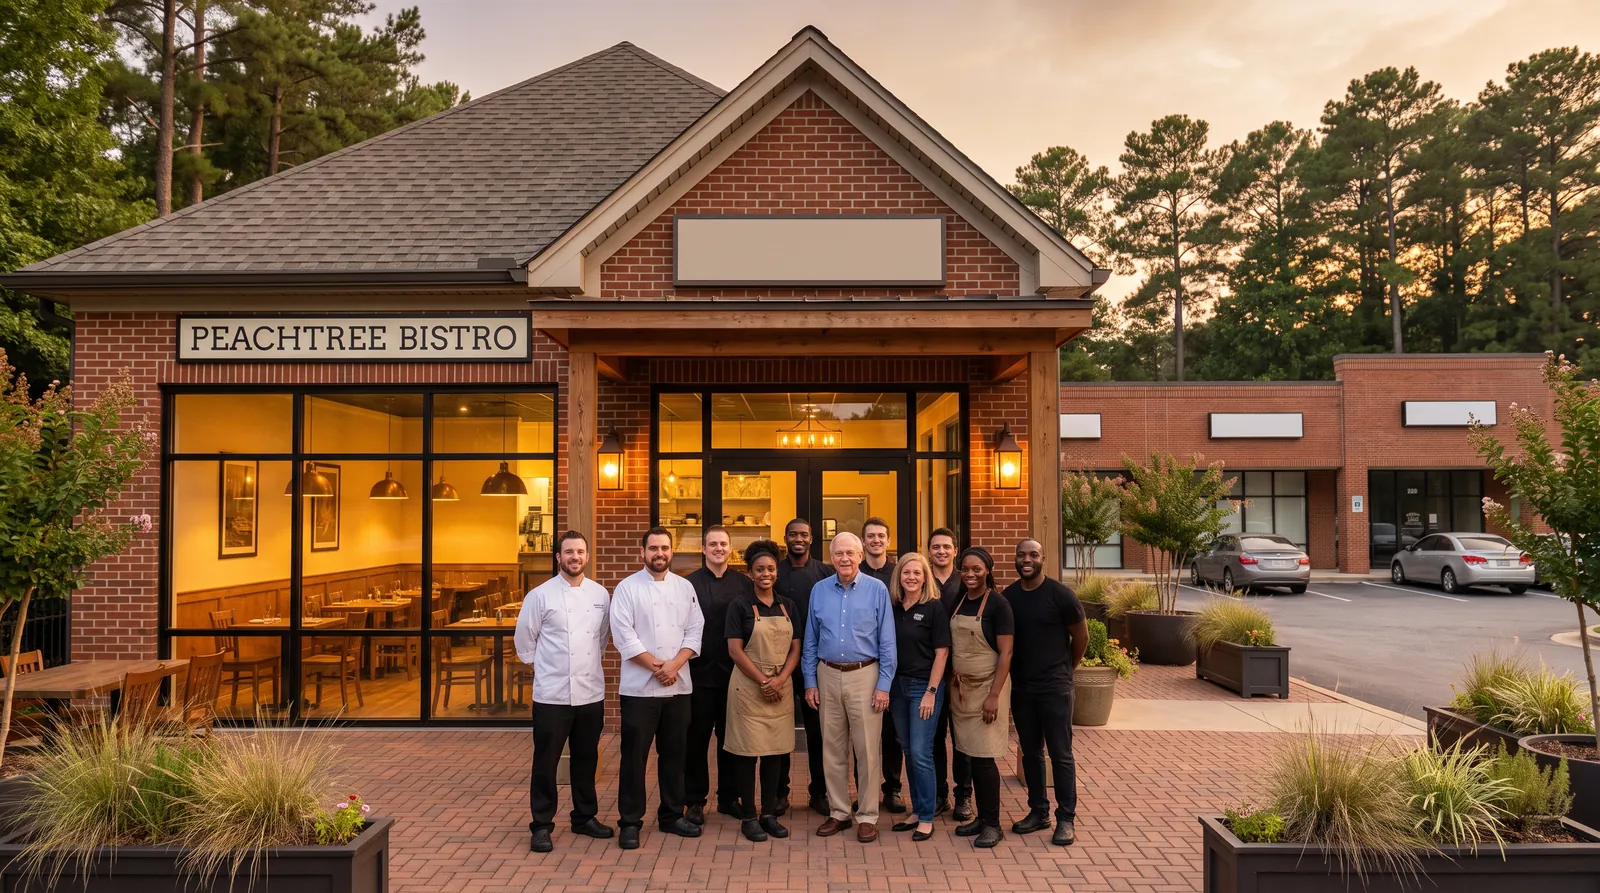
A small business owner and staff outside their restaurant
Home / Business Insurance

Georgia Business Insurance: Comp comes first. The rest should be on purpose.

Georgia requires workers' comp once you have three or more employees. Everything after that is judgment: what you do, who you employ, and what your landlord and clients demand. Let's build it right.

3+
Workers: Comp Required In GA
25/50/25
Min. Liability On Work Vehicles
30+
More Carrier Options
Free
Coverage Review With A Local Agent
The Quick Answer

Georgia requires workers' compensation for any business with three or more workers, and that count includes regular part-time workers (State Board of Workers' Compensation; O.C.G.A. 34-9-2). Business vehicles need commercial auto with at least 25/50/25 liability; Georgia is an at-fault state, and uninsured motorist coverage is included unless you reject it in writing. Personal auto policies typically exclude business use. A Business Owners Policy, which bundles property and general liability, is not required by law, but most leases and client contracts require it in practice. Georgia's severe storms and tornadoes make commercial property wind deductibles worth reading closely. All Access Agency, a local insurance agency in Morrow, starts with our primary carrier and can access 30+ other carriers through brokerage relationships for commercial and hard-to-place risks. Free quotes at (770) 576-3416.

Workers' comp
Required at 3+ employees, part-time included
Work vehicles
25/50/25 + UM unless rejected in writing
Most small firms
BOP + comp, built on purpose
Free quotes
(770) 576-3416
Georgia Business Insurance, The Short Version

Comp is the law. Everything else is judgment.

Start with the part that isn't optional. Georgia requires workers' compensation for any business with three or more workers, including regular part-time workers. That is how the State Board of Workers' Compensation puts it, and the statute (O.C.G.A. 34-9-2) exempts only employers with fewer than three employees regularly in service. Part-timers count. If you are at two employees and hiring, plan for comp now and let us confirm where you stand.

Comp is what keeps a workplace injury from becoming a business-ending event. Injuries run through the comp system, with defined benefits for the employee and defined costs for you. Pricing runs on payroll and class codes, and a wrong code can quietly overcharge you for years or surprise you at audit. Getting the classification right is one of the first things we check.

Vehicles come next. If the business owns it, it needs commercial auto, and in Georgia that means at least 25/50/25 liability, the same floor as any registered vehicle. Georgia is an at-fault state, so the driver who causes a crash pays for it, and uninsured motorist coverage stays on the policy unless you reject it in writing. If you drive your own car for work, know that personal auto policies typically exclude business use. Mithferson is a former personal and commercial auto claims adjuster, so he knows how these claims actually play out.

Everything after that is judgment, and judgment is what you are hiring us for. Most small Georgia businesses run on a Business Owners Policy that packages property and general liability. The law doesn't require it, but your landlord and your clients almost always will. Give advice for money and you need professional liability. Hold customer data and cyber stops being a luxury. Own a building in tornado and thunderstorm country and the wind and hail deductible deserves a hard look. We start with our primary carrier, and through brokerage relationships we can also access 30+ other carriers when it isn't the right fit. Commercial is where that matters most, and it is why we rarely have to say no. Nothing on this page is legal advice; for employment-law questions, talk to an employment attorney. We handle the insurance.
What a business actually needs. In the order it matters.

One of these is the biggest decision on the page. The rest depend on what you do, who you employ, and what you would lose on your worst day.

Required by law
Required

Workers' Compensation

Georgia requires comp once a business has three or more workers, regular part-time workers included. Injuries run through the comp system with defined benefits instead of open-ended exposure. Headcount changes, so check with us before assuming you are under the line.

Start here
BOP

Business Owners Policy

Bundles commercial property and general liability into one package built for small and mid-sized firms. Georgia law doesn't require it, but most leases and many client contracts require the coverage inside it. Usually cheaper than buying the pieces separately.

Core
$1M / $2M

General Liability

The slip and fall, the damage you cause at a client's site, the advertising injury claim. Covers defense costs as well as the judgment. It is also what your landlord and your clients will demand a certificate for before you can sign anything.

Core
Reopen

Business Income

Property coverage rebuilds the building. This pays your rent, payroll, and lost profit while that happens. After a big Georgia storm, roofers and contractors book up fast, so set the restoration period to a realistic timeline.

If you advise
E&O

Professional Liability

General liability covers bodily injury and property damage. It does not cover being wrong. If clients pay you for expertise and a mistake could cost them money, you need this, and around here your contracts will probably require it anyway.

As you grow
Umbrella

Commercial Umbrella

Extra liability limits that sit above your general liability, commercial auto, and employer's liability. One serious crash or injury claim can outrun a $1M policy, and larger contracts often ask for more than a BOP alone provides.

Not covered
Your Car

Business Use On A Personal Policy

Personal auto typically excludes business use. If the vehicle belongs to the business, it needs commercial auto with at least 25/50/25 liability, and UM unless you reject it in writing. If staff drive their own cars for you, add hired and non-owned coverage.

Watch this
Wind

Wind & Hail Deductibles

Georgia averaged about 17 tornado events a year from 2001 to 2020, per GEMA, on top of hail and the inland wind from tropical storms. Many commercial property policies carry a separate wind and hail deductible, sometimes figured as a percentage of the building's value. Know yours before the storm, not after.

If you hold data
Cyber

Cyber Liability

Breach notification, forensics, legal counsel, extortion, and the income you lose while locked out. Small businesses get targeted precisely because attackers assume the defenses are thinner. Breach-notification laws add real deadlines the moment customer data is exposed.

About to hire your third employee? Set up comp first.

Georgia requires workers' comp at three or more workers, regular part-timers included. Fifteen minutes on your payroll and job duties gets you the right class codes and a real price. Free, no pitch.

Required In Georgia

Georgia workers' comp, in plain English.

This is the coverage the state doesn't leave up to you. So the useful questions are who counts, how it is priced, and how to keep it clean.

Who has to carry it

The State Board of Workers' Compensation puts it plainly: comp is required for any business with three or more workers, including regular part-time workers. The statute, O.C.G.A. 34-9-2, exempts employers with fewer than three employees regularly in service. That line is not as clean as it sounds once seasonal help, part-timers, and family members enter the picture. If you are not sure where you fall, ask before you hire, not after an injury. The Board itself is reachable at (404) 656-3818 or toll-free at (800) 533-0682.

What it does for you

Comp pays an injured employee's medical bills and lost wages through a defined system. That structure protects the employee, and it protects the business from the open-ended cost of an injury with nothing behind it. Self-insuring is an option the law allows, but it generally fits larger employers with the financial depth to carry their own claims. For most small and mid-sized businesses, an insured policy is the practical route.

Getting the price right

Comp pricing runs on class codes. Clerical staff and roofers are priced very differently per $100 of payroll, and misclassified payroll is the most common way businesses overpay or get an ugly surprise at audit. We check classifications, estimate payroll honestly, and help you stay ready for the year-end audit.

The paperwork nobody mentions

Certificates of insurance, additional-insured endorsements, and waiver-of-subrogation requests are daily work for contractors and service businesses across south metro Atlanta, and slow certificates stall invoices. We handle them routinely. About one in ten of the households we insure also owns a business, so this is everyday work for our office, not a side line. On employment-law questions, talk to an employment attorney. We do the insurance.

Not sure if your class codes are right?

Workers' comp is priced on payroll and classification, and a wrong code quietly overcharges you for years. It is one of the first things we check. Free either way.

Whatever you built. We'll cover it properly.

The right program depends on what you do, not what size you are. Here is where the differences bite.

Need a certificate of insurance today?

Landlord, GC, or client waiting on one? Send us the contract language and we will turn it around fast, with the right additional insured wording rather than a guess.

Business insurance in Morrow. And across south metro Atlanta.

Our office is on Southlake Pkwy in Morrow, near I-75 and Southlake Mall, close to the Clayton and Henry county businesses we insure. Tell us where you operate anywhere in Georgia.

Georgia business insurance questions. Straight answers.

Do I need workers' compensation insurance in Georgia?

If you have three or more employees, yes. The State Board of Workers' Compensation says comp is required for any business with three or more workers, including regular part-time workers.

The statute, O.C.G.A. 34-9-2, exempts employers with fewer than three employees regularly in service. Headcounts move with seasons and part-time help, so confirm where you stand before you skip coverage.

Do part-time employees count toward the three?

Yes. Georgia's requirement counts regular part-time workers, not just full-time staff.

Part-time and seasonal help is exactly where small businesses get caught out. Report all payroll accurately so the policy and the year-end audit match reality.

I have fewer than three employees. Do I still need workers' comp?

Georgia law generally does not require it below three employees regularly in service.

Practically, the general contractors and clients you work for may require a certificate showing comp coverage before you start on their job. And once you reach three workers, part-time included, the requirement applies to you.

What is a BOP, and is it required?

A Business Owners Policy bundles commercial property and general liability, usually with business income, into one package priced for small and mid-sized firms. Georgia law does not require it.

Your landlord and clients usually do: most commercial leases and many client contracts require property and liability coverage before you sign. A BOP is not enough by itself if you give professional advice, hold sensitive data, own vehicles, or have employees who need comp.

What insurance do business vehicles need in Georgia?

A vehicle the business owns needs commercial auto with at least 25/50/25 liability: $25,000 per person and $50,000 per accident for injuries, and $25,000 for property damage. Georgia is an at-fault state, and uninsured motorist coverage is included unless you reject it in writing.

Those are minimums. A work truck or van in a serious crash can blow through 25/50/25 quickly, so most businesses carry much higher limits. For-hire, trucking, and DOT-regulated operations have additional filing requirements, and we will walk through them with you.

Does my personal auto policy cover me driving for work?

No. Personal auto policies exclude business use: deliveries, hauling tools between sites, driving clients.

If the vehicle belongs to the business, it needs commercial auto. If employees drive their own cars on your errands, you need hired and non-owned auto coverage, because their accident on your errand can become your claim.

I run my business from home. Doesn't my homeowners policy cover it?

Mostly no. Homeowners policies carry a small sub-limit for business property and generally exclude business liability outright. A client who trips on your front step is not a covered claim.

The fix is cheap: an endorsement or a small in-home business policy. The expensive version is finding out after the claim.

A client wants a certificate of insurance naming them as additional insured. What is that?

A certificate of insurance is proof of your coverage; naming a client as additional insured extends your liability policy to protect them for work you do for them.

It is standard in construction, services, and property-management work around south metro Atlanta. We turn certificates around quickly, because a stalled certificate stalls your invoice.

What is professional liability, and do I need it?

General liability covers bodily injury and property damage.

It does not cover being wrong. If clients pay you for expertise or advice, such as consulting, design, inspections, or bookkeeping, and a mistake could cost them money, professional liability (errors and omissions) is what responds, and your contracts will often require it anyway.

Do I need cyber insurance if I'm not a tech company?

If you hold customer data, take cards, or run your operations through email and cloud software, you have cyber exposure.

Small businesses are targeted precisely because attackers assume thin defenses. Breach-notification laws carry real requirements and deadlines, and cyber coverage pays for the forensics, notification, legal counsel, and the income you lose while locked out.

How do wind and hail deductibles work on commercial property?

Many commercial property policies carry a separate wind and hail deductible, sometimes a flat dollar amount and sometimes a percentage of the building's insured value.

In Georgia that matters. GEMA counted 343 tornado events in the state from 2001 to 2020, and tropical systems bring inland wind and flooding during hurricane season, June 1 to November 30. Read the deductible before storm season, and we will show you what a claim would actually cost you out of pocket.

What if my type of business is hard to place?

Then we keep going. We start with our primary carrier, and through brokerage relationships we can also access 30+ other carriers, which matters most for commercial, specialty, and hard-to-place risks.

Depending on the risk, that can include carriers such as Progressive Commercial, The Hartford, Travelers, Liberty Mutual, CNA, and Hiscox. Availability depends on the risk, but our goal is simple: we rarely say no without finding you an option.

How much does business insurance cost in Georgia?

It ranges too widely for one honest number: a home-based consultant and a restaurant with a building and a delivery van are different animals.

Directionally, workers' comp is priced per $100 of payroll by class code, a BOP scales with your property and what you do, and commercial auto depends on the vehicles and drivers. We quote our primary carrier first, compare it with other carriers we can access when that makes sense, and show you the options clearly.

Still have questions? Call (770) 576-3416. We will give you a straight answer.

Tell us what you built.
We'll tell you what it needs.

What you do, who works for you, what you drive. We will build the program around the business, including the parts you can skip. It takes about 15 minutes to get started.